Gerald - Cash Advance

Screenshots
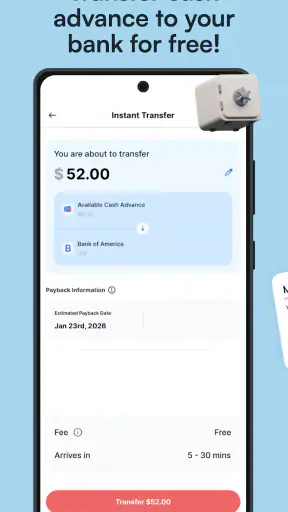
Details
- Rating
- 4.23K reviews
- Version
- 69.0.9
- Developer
- Gerald Technologies, Inc.
Analysis by Norviv
When a small expense lands before payday, I understand why a cash-advance app can feel more practical than reaching for a credit card. Gerald - Cash Advance is a finance app from Gerald Technologies, Inc. that focuses on getting access to cash without a traditional credit check or interest charge. I see its strongest use case as a short-term household gap: a grocery run, a transport expense, or an urgent bill that cannot comfortably wait.
My overall impression is positive but cautious. The app is free to install, aimed at Everyone, and has built a sizeable audience, with over 500 thousand installs. Its average rating sits at 4.4 from around 10 thousand ratings, which suggests that many people find the basic idea useful. Still, a cash advance is not extra income. The important question is whether it helps you manage a timing problem without creating a new one when repayment arrives.
How Gerald fits into a shared household
The most realistic way I would use Gerald is privately, even if the phone itself is shared. Imagine two adults managing a household budget from the same device. One person notices that the account is short before a necessary purchase, while the other is expecting the next deposit to cover rent and utilities. In that situation, opening the app can help the person responsible for the immediate expense review the available option directly rather than turning the household conversation into guesswork.
That shared-device scenario also reveals an important boundary: a finance app should not be treated like a family shopping app. I would avoid passing the phone around casually after signing in, and I would not assume that another household member should be able to inspect the account simply because they share the device. Gerald is designed around an individual financial relationship, so household coordination still depends on clear communication between people.
I found the app’s appeal easiest to understand when the need was specific and temporary. If I knew exactly why I needed the money and when the regular budget would absorb the repayment, the advance could be a useful bridge. If I was already using advances to cover ordinary living costs every week, I would see that as a warning rather than a successful budgeting strategy.
The practical rule I would use is simple: borrow only for a defined gap, not for an undefined shortage. Before requesting anything, I would write down the expense, the amount already available, and the money that must remain untouched for essential bills. That small pause matters more than the speed promised by any cash-advance service.
What the setup means for account boundaries
Gerald presents itself as a fast alternative to conventional borrowing, and the no-credit-check approach may be attractive to someone who does not want a hard credit-focused process for a small emergency. The trade-off is that convenience should not be confused with universal eligibility or unlimited access. I would expect the app to evaluate the account and the request within its own rules, so I would not plan a bill around an advance until the app actually shows what is available.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That distinction is especially important in a household. If one person installs the app and another assumes the money will definitely be available, the result can be an awkward conversation at the worst possible moment. I would keep the request, the intended use, and the repayment timing visible to the adults who share responsibility for the budget, while keeping login details and personal account access private.
The app is free, which lowers the barrier to trying it, but free installation does not mean that every financial action is costless in every possible circumstance. I would read each screen carefully before confirming a request and check the repayment details rather than relying only on the headline promise of no interest. The safest habit is to treat the confirmation screen as the final source for the particular transaction being considered.
For someone setting up the app on a shared phone, I would first make sure the device has a screen lock and that notifications cannot reveal sensitive financial information on the lock screen. I would also avoid saving access details where another person can see them. These are not special Gerald features; they are sensible boundaries for any app handling personal finances.
Coordinating money without turning the app into a family account
Gerald can support a conversation, but it does not replace one. In a household, I would use it as a prompt to agree on three things: what the advance is for, who is responsible for repayment, and which upcoming expense takes priority. That is more useful than simply announcing that cash is available.
For example, suppose one adult needs money for a necessary prescription while the other is waiting for a paycheck. The first person could explain the immediate need, confirm that the repayment will not interfere with rent or utilities, and then make the decision from their own account. The other person does not need unrestricted access to the app to understand the household impact. A short, specific agreement is usually safer than sharing passwords or leaving the app open.
I also like the idea of separating “available now” from “safe to spend.” An amount shown inside a cash-advance app may solve today’s problem, but it can still reduce flexibility later. When coordinating with a partner, I would calculate the household’s next fixed obligations first and only then decide whether the advance is sensible. This approach prevents the app from quietly becoming part of the normal monthly income.
Another useful habit is to record the purpose outside the app, perhaps in a private household budget note. I would write something like “car repair gap” or “food until payday,” along with the expected repayment date. That makes it easier to spot repeated use. If the same category appears again and again, the underlying issue may be an irregular bill, an income mismatch, or a budget that needs restructuring. Gerald may help with the immediate timing, but it cannot solve that larger pattern by itself.
Compared with asking a friend or relative for money, the app can feel less socially uncomfortable because the request is handled through a financial service. Compared with a credit card, its no-interest positioning may look more predictable for a brief gap. But personal borrowing can offer more flexibility in some households, while a credit card may be more suitable for a purchase that needs a longer repayment plan and stronger purchase protections. I would choose based on the full repayment situation, not just the speed of access.
Age, trust, and responsible use
The Everyone content rating tells me that the app’s presentation is not restricted to mature audiences in the way a game with explicit content might be. That should not be mistaken for a recommendation that children manage cash advances. Finance decisions require legal capacity, personal responsibility, and a clear understanding of repayment. In a family setting, I would keep the account with the adult whose name and finances are actually involved.
This is where trust matters more than convenience. I would not let a child or teenager use an adult’s logged-in finance account, even for a seemingly harmless request. I would also be careful when helping an older relative: explaining what each screen means is reasonable, but submitting a request on someone else’s behalf without their informed approval is not. The person receiving the financial service should understand the amount, purpose, and repayment obligation.
Gerald was released on July 8, 2021, and the current version is 69.0.9. The app supports Android starting with version 7.0, so it is accessible on many older devices. That can be helpful in a household where not everyone has a recent phone, but older hardware can also make account privacy more important. I would update the app through the normal store process, keep the operating system as current as the device allows, and avoid using an old shared phone that no longer receives security updates for sensitive financial activity.
I would also avoid interpreting a good rating as a guarantee that the experience will be identical for every user. Gerald has around 4.2 thousand written reviews alongside its broader rating count, and individual financial situations vary considerably. A person with irregular income, several existing obligations, or a history of relying on advances may experience the service very differently from someone handling one isolated emergency.
Where the app is genuinely useful
In my view, Gerald is most useful when the amount needed is modest, the reason is concrete, and the next incoming money is dependable. A household that has temporarily mistimed a necessary purchase may appreciate the speed and the possibility of avoiding interest. Someone who dislikes opening a conventional credit account for a small shortfall may also prefer this type of focused tool.
The no-credit-check positioning can be particularly appealing to people who are worried about the effect of a traditional credit application. Even so, I would not use that feature as an excuse to skip affordability checks. Credit history is only one part of financial health. The more important question is whether the upcoming budget can absorb repayment without another advance.
I would also consider Gerald when coordinating an unexpected household expense that has a clear owner. If one person is responsible for a car-related cost and has the income to repay it, keeping the transaction connected to that person’s account may be cleaner than mixing it into a shared credit card. That arrangement reduces confusion, provided both adults agree on the household consequences.
The app is less convincing for planned purchases, recurring subscriptions, or expenses that can wait. In those cases, saving first, negotiating a due date, or using a normal budgeting method is usually healthier. It is also not the right substitute for a long-term emergency fund. A cash advance can smooth timing; it cannot create financial resilience.
Friction and limitations I would take seriously
The first limitation is psychological: fast access can make borrowing feel smaller than it is. A few taps may remove the pause that normally forces me to question a purchase. I would deliberately add my own pause by checking the next two weeks of bills before confirming anything.
The second is household visibility. If only one adult knows about the advance, the shared budget can become misleading. That does not mean everyone should share account credentials. It means the people affected by repayment should know the relevant amount and timing. Privacy and transparency are separate issues, and a well-managed household needs both.
The third limitation is that “no interest” does not automatically make an advance the cheapest or safest option in every situation. I would compare the complete terms shown for the request with alternatives such as delaying a nonessential purchase, asking a provider for an extension, or using savings. If the app’s conditions are not clear to me on the confirmation screen, I would stop rather than rush.
I would skip Gerald if I needed a larger, structured loan with a clearly defined long repayment schedule. In that case, a regulated lending product with transparent installments may be easier to plan, even if the application process takes longer. I would also skip it if I had no reliable way to repay. An advance cannot fix a permanent income gap, and repeated short-term borrowing can make that gap harder to escape.
My household verdict
After looking at Gerald as both a personal finance tool and a shared-household complication, I see it as a useful emergency bridge rather than a general-purpose money source. The free app, accessible Android requirements, no-credit-check approach, and no-interest positioning make it worth considering for a narrowly defined shortfall. The developer, Gerald Technologies, Inc., has built something that speaks directly to people who want a quick alternative to traditional credit.
My recommendation comes with a firm condition: decide the repayment plan before requesting the advance. Tell the household members who will be affected, keep the account private, and use the app only when the expense is necessary and the timing problem is temporary. If the same need keeps returning, move the conversation away from another advance and toward a budget change, an emergency fund, or professional financial guidance.
For a single adult managing a brief gap, Gerald may be more convenient than asking for help or opening a credit product. For a couple, it can work when responsibility is clearly assigned and the repayment is included in the shared plan. For a child, an untrusted household member, or anyone already depending on advances to cover regular expenses, I would not recommend it.
That balance is why I would describe Gerald - Cash Advance as practical but not effortless. It can make an urgent moment easier, yet the real value comes from using it with boundaries. If you can explain exactly why you need the money, identify where repayment will come from, and keep the decision honest with the people sharing your budget, it is a reasonable app to consider. If you cannot answer those questions, waiting and choosing a slower alternative is the better financial decision.
Frequently Asked Questions
01What is Gerald - Cash Advance, and how does it work?
Gerald is a financial app designed to give eligible users access to a cash advance before their regular payday. After creating an account and completing the required identity and financial checks, you may see an available advance limit in the app. If approved, the money can be transferred according to the available delivery options, terms, and eligibility rules shown before confirmation.
02Who can use Gerald, and what requirements must I meet?
Availability depends on factors such as your age, residential location, identity verification, linked bank account, income activity, and account history. Gerald may also require access to transaction information to evaluate eligibility. Meeting the basic requirements does not guarantee approval, because advance limits and access can change based on the app’s internal review and your financial profile.
03How much does Gerald cost, and are there hidden fees?
Before requesting an advance, carefully review the repayment amount, delivery charges, membership costs, optional features, and any other fees displayed in the app. The total cost may depend on how quickly you want to receive the money and which services you use. Do not assume every transfer is free; read the final disclosure and subscription terms before accepting.
04How and when do I repay a Gerald cash advance?
Repayment is generally scheduled for a future date connected to your expected income or the terms presented when you request the advance. The app may use a linked bank account or another authorized payment method to collect the amount owed. Make sure sufficient funds are available, and check the repayment date, extensions, failed-payment consequences, and cancellation options in the agreement.
05Is Gerald safe to use, and what should I check before downloading it?
Gerald may request sensitive information, including identity details, banking credentials, and transaction data, so review its privacy policy, permissions, security practices, and user agreement before signing up. Download the app only from an official Google Play or Apple App Store listing. Also verify the developer name, current ratings, support contacts, and whether the service is available in your region.


